Discover if your service qualifies you for exclusive home buying benefits and significant savings with the Oregon Homes for Heroes program. From Portland’s largest employers to rural communities, thousands of Oregon professionals are eligible.
If you’re reading this, you’re likely wondering whether your profession qualifies as a hero for the substantial savings available through Oregon’s Homes for Heroes program. With heroes saving an average of $3,800 through the Homes for Heroes program, understanding eligibility requirements can be the difference between paying full price and saving thousands on your home purchase.
As Oregon’s loan specialist in hero mortgage programs, I offer comprehensive mortgage solutions and help heroes from every corner of the state – from Portland firefighters to Bend nurses to Salem teachers -navigate the qualification process and maximize their benefits. This comprehensive guide will walk you through exactly who qualifies, what documentation you’ll need, and how to verify your eligibility across Oregon’s diverse employment landscape.
Serving Heroes Across Oregon’s Major Metro Area
Oregon’s hero population is concentrated in our major metropolitan centers, and the Homes for Heroes program is built to serve them all. From the vast Portland Metro Area – including Beaverton, Hillsboro, and Gresham —to the state’s largest hubs in the Willamette Valley (Salem, Corvallis, Albany, and Eugene), and down to Southern Oregon (Medford/Ashland) and Central Oregon (Bend/Redmond/Prineville), your hero status qualifies you for these benefits regardless of your city.
We are here to simplify the mortgage process for heroes serving in every Oregon community, ensuring you get the savings you’ve earned right where you live and work.
The Five Hero Categories: Who Qualifies as a Hero in Oregon
The Homes for Heroes® Oregon program recognizes five essential professions that serve our communities. We break down each category below, featuring specific Oregon examples and major employers.
Hero Category
Who Qualifies
Oregon Employer Examples
🚒 Firefighters & EMS
Career and volunteer firefighters and EMS personnel, EMTs, Paramedics, and 911 dispatchers. You are a first responder.
Portland Fire & Rescue, Tualatin Valley Fire & Rescue, Bend Fire & Rescue, Eugene Springfield Fire.
OHSU (Oregon Health & Science University), Legacy Health, St. Charles Health System, PeaceHealth (Eugene).
📚 Educators
Teachers (K-12), school administrators, support staff, and university/college employees.
Portland Public Schools, Salem-Keizer School District, University of Oregon, Oregon State University.
Comprehensive Mortgage Solutions: Learn How You Can Save Money
The Homes for Heroes program is a non-profit program designed to say “thank you” to our local heroes. By choosing to work with a participating lender like me, you are guaranteed to receive Hero Rewards®.
Heroes Save Thousands: Hero Rewards Explained
When you partner with a Homes for Heroes® affiliate for your home purchase, you receive a substantial reward after closing.
Hero Rewards Benefit
Financial Impact
Key Service Provider
Lender Savings
Discounted closing costs and fees. This is how we help you save money and make homeownership more accessible.
Your lender (Shannon McAlister, Mortgage Specialist).
Real Estate Agent
Cash back/reward on the price of the home after closing.
Participating real estate agent (The Homes for Heroes real estate network).
Total Savings
Average Heroes Save over $3,800.
Entire Homes for Heroes team working together.
The Homes for Heroes Oregon team is dedicated to serving heroes. We can also connect you with a participating real estate agent who will help you save even more money when you buy or sell a home.
A Way to Give Back to the Community
Choosing to use Homes for Heroes is an indirect way to give back. A portion of every Homes for Heroes affiliate’s earnings goes to the Homes for Heroes Foundation. This foundation awards hero grants to local heroes and provides housing or emergency financial assistance to those facing challenges. Every time a hero buys or sells a home with Homes for Heroes, they are helping heroes in need, fulfilling a commitment to give back to the community.
Having your documents ready is the key to a fast qualification and a smooth closing for your home loan.
Core Documents Required for All Heroes:
✅ Government-Issued Photo ID
✅ Current Employment Verification
Specialized Documentation & Programs
Homes for Heroes can be paired with all mortgage types, speciality programs, down payment assistance and grants:
Military and Veterans: We specialize in VA Loans and require a current LES or DD-214.
Law Enforcement/Fire/EMS: You are a first responder who may be eligible for programs like the Federal HUDGood Neighbor Next Door Program.
First-Time Home Buyer Programs: Even if you’re a first-time home buyer, your hero status can be combined with other downpayment assistance options.
Ready to Verify Your Qualification and Hero Savings?
Your daily commitment to serving others has earned you these homeownership benefits. Oregon Homes for Heroes makes homeownership more accessible.
Ready to achieve your dream home with significant savings? Contact Oregon mortgage lender Shannon McAlister, Oregon’s specialist in hero mortgage programs. With extensive experience working with heroes from every profession, Shannon can quickly verify your eligibility requirements and explain exactly how much you can save money when buying.
Contact Shannon McAlister – Oregon Heroes Mortgage Specialist 📧 Contact Today through home-owners-pdx.com 🏠 Serving qualified heroes throughout Oregon – Expert in eligibility verification and benefit maximization
This eligibility guide provides current information as of September 2025. Program requirements may change. Always verify current eligibility criteria with official program representatives and qualified mortgage lenders.
If you’re a firefighter, police officer, teacher, healthcare worker, or active military or veteran in Oregon, there’s a home buying program that puts real money back in your pocket. Not a gimmick. Not a complicated grant application. Just straightforward savings on one of the biggest transactions of your life.
Homes for Heroes is a nationwide network of real estate agents and mortgage lenders who give back to the people who serve our communities by discounting their fees. I’ve been an Oregon Homes for Heroes affiliate for over 12 years. Here’s how it works, who qualifies, and what it saves you in Oregon’s current market.
About the Program
What Is Homes for Heroes?
Homes for Heroes is a program founded after 9/11 that connects qualifying heroes with a network of real estate professionals – agents, lenders, title companies – who offer reduced fees and cash back at closing. There’s no special loan product and no separate application. Choose the home you want and whatever mortgage is the right one for you. There are no restrictions on property type or location. The savings come from the fees of the affiliated professionals you work with.
The numbers: heroes save an average of $3,000 when they buy or sell a home, and $6,000 if they do both. In May 2025, the average hero saved $3,832 through the program. That’s real money that shows up as a check in your hands 5-7 days after closing.
$3,832
Average hero savings May 2025
$3K
Average savings buying or selling
$6K
Average savings buying and selling
0.7%
Realtor reward on purchase price
How the savings break down:
Realtor Reward
0.7% of purchase price back to you after closing
+
Lender Savings
Reduced mortgage fees from your HFH mortgage specialist
=
Your Total Savings
$3,000–$6,000 average per transaction
No restrictions on loan type
Homes for Heroes savings apply to Conventional, FHA, VA, USDA, DSCR, Jumbo, and reverse mortgages. Purchase or refinance. It layers on top of whatever mortgage program you’re already using.
Who Qualifies
Who Qualifies in Oregon?
Five professions qualify. If you work in one of these fields, active, retired, or in some cases part-time, you likely qualify. The program is broader than many assume.
Firefighters and EMS
Career and volunteer firefighters
EMTs and paramedics
Fire department administrative staff
Law Enforcement
Police officers (city, county, state)
Sheriff’s deputies
Corrections officers
Dispatchers and 911 operators
Federal law enforcement
Active or retired
Military
All branches, active and reserve
National Guard members
Veterans with honorable discharge
Military spouses
Healthcare
Nurses (RN, LPN)
Doctors and physician assistants
Healthcare technicians and hospital administrative staff
Mental health professionals
Active or retired
Educators
K-12 teachers
School administrators, counselors, librarians
University employees
Often Overlooked
These roles qualify, too: 911 dispatchers, BOEC employees, corrections officers, and hospital administrative staff. Retired heroes in all five categories qualify as well. Just ask, you may be surprised.
What You Save
What Does It Save You in Oregon?
The realtor reward is 0.7% of the home purchase price. Here’s what that looks like across Oregon markets, based on Realtor.com median price data from August 2025:
Portland Metro ~$3,675
$525,000
PPB, OHSU, Portland Fire, PPS teachers
Bend ~$6,125
$875,000
St. Charles Health, Central Oregon heroes
Eugene ~$3,605
$515,000
UO, LCC, PeaceHealth, Eugene Police & Fire
Salem ~$3,430
$490,000
State employees, OR State Hospital, Salem-Keizer schools
Hillsboro ~$3,710
~$530,000
Tech corridor first responders, healthcare
Beaverton ~$4,823
~$689,000
Tech corridor heroes, educators, healthcare
These figures are the realtor reward only. Lender savings are separate and applied at closing. The combined savings is what gets heroes to that $3,000-$6,000 average range.
Buying and selling?
If you use a Homes for Heroes realtor to sell your current home and buy your next one, the 0.7% reward applies to both transactions. The average hero doing both saves $6,000.
How It Works
How It Works: Step by Step
No separate loan application, no eligibility quiz, no waiting for a government program to approve you.
You can do this through me directly. I verify your eligibility and connect you with the program.
To receive the full realtor reward, your real estate agent needs to be a Homes for Heroes affiliate. I can refer you to vetted affiliated agents throughout Oregon.
Use any mortgage that is right for you – Conventional, FHA, VA, USDA, or any other program. The Homes for Heroes savings are separate from your loan program selection.
Lender savings are applied at closing. The realtor reward arrives as a check 5-7 days after closing.
The only moving part that catches people off guard: you need both an affiliated realtor and an affiliated lender to get the full benefit. If your agent isn’t a Homes for Heroes affiliate, you leave the realtor reward on the table. Worth knowing before you commit to an agent.
Income and Qualification
Hero Income and Mortgage Qualification
Homes for Heroes works with any mortgage program. Hero income often comes in a variety of forms – base wages, overtime, shift differential, pension, BAH, 1099 income – and each one qualifies for mortgage purposes in its own way. Knowing how your income is calculated before you start the process puts you in a better position from day one.
Law Enforcement / Fire
Base wages qualify
Overtime: 2-year history required
Shift differential: same as overtime
Secondary employment: documented separately
PERS contributions don’t reduce qualifying income
Military / Veterans
Base pay qualifies
BAH counts as qualifying income
VA loan: zero down, no PMI
Military spouses qualify for the program
Healthcare
Base wages qualify
Shift differential: 2-year history may be required
Overtime: 2-year history required
Locum / 1099: documented separately
Travel nurses: plan ahead with lender
Educators
Salary income straightforward
W-2 documentation standard
Summer closings: confirm fall employment early
Between contracts: plan documentation in advance
Law Enforcement and First Responders
Police officers, firefighters, and other first responders typically earn base wages plus overtime, shift differential, and sometimes secondary employment income. Each component qualifies differently for mortgage purposes. Overtime can be counted if it has a documented two-year history. Shift differential is treated similarly. Secondary employment – security details, private work – requires its own documentation trail.
Oregon PERS pension contributions don’t affect your gross qualifying income; you qualify on what you earn before contributions. If you’re near retirement and transitioning to pension income, advance planning is important. For a deeper look at how law enforcement income and benefits work in a mortgage context, see the Home Buying Guide for Oregon Police Officers and Law Enforcement Professionals.
Military and Veterans
Veterans are the clearest case for combining Homes for Heroes with another program. VA loans offer zero down payment, no monthly mortgage insurance, and competitive rates. Combined with Homes for Heroes savings – the realtor reward and lender fee reductions – veterans can close with very little out of pocket and walk away with a check. Basic Allowance for Housing (BAH) counts as qualifying income. Military spouses qualify for the program regardless of whether they’re the veteran.
Healthcare Workers
Nurses, physicians, and hospital staff often have shift differential income, overtime, and in some cases 1099 income from locum or travel nursing work. All of these qualify for mortgage purposes with proper documentation. Travel nurses face additional documentation requirements because income may vary by contract. Planning ahead with your lender matters here more than in almost any other profession.
Educators
Teacher income is generally straightforward: documented salary, W-2, predictable. The timing consideration for educators is the academic calendar. Closing during summer or between contracts requires documentation that confirms continued employment for the fall. Worth flagging to your lender early so the documentation is ready when you need it.
Combining Programs
Combining Homes for Heroes with Other Oregon Programs
Homes for Heroes savings can be combined with any other program you qualify for. It doesn’t compete with anything.
VA Loans
Best for: Veterans and military
Zero down payment. No monthly mortgage insurance. Competitive rates. Pairs directly with Homes for Heroes, realtor reward and lender savings on top of VA benefits.
FHA Loans
Best for: Earlier career, credit challenges
Lower credit score thresholds and higher allowable debt ratios. Homes for Heroes applies without restriction.
Down Payment Assistance
Best for: Limited cash to close
Oregon state, county, and local DPA programs. Varies by income, price, and location. Homes for Heroes savings apply on top.
IDA Programs
Best for: Early savers with lead time
Oregon IDA Initiative matches savings toward a home purchase. Has enrollment periods – worth knowing about early. Works alongside Homes for Heroes.
VA Loans for Veterans and Military
Zero down payment. No monthly mortgage insurance. Competitive rates. Veterans eligible for a VA loan should default to it unless there’s a specific reason not to. Homes for Heroes layers on top. The program doesn’t restrict or reduce VA benefits in any way.
FHA Loans
Heroes earlier in their careers, or those with credit challenges, sometimes do better with FHA than Conventional. FHA’s lower credit score thresholds and higher allowable debt ratios can be the difference between qualifying now versus waiting. Homes for Heroes applies to FHA loans without restriction.
Down Payment Assistance
Oregon has several down payment assistance programs available to qualifying buyers, including heroes. These are offered through state, county, and local agencies and vary by income, purchase price, and location. Homes for Heroes savings apply on top of DPA programs, they don’t compete. If you think you might qualify for down payment assistance, bring that up early in our conversation so we can factor it into your full picture.
Individual Development Accounts (IDAs)
Oregon IDA Initiative programs allow qualifying participants to save toward a home purchase and have those savings matched. If you’re in an IDA program or think you might qualify, this can work alongside Homes for Heroes benefits. These programs have enrollment periods and lead time requirements, worth knowing about early.
Oregon Markets
Where Oregon Heroes Are Buying
Portland Metro
Portland and the surrounding metro – Beaverton, Hillsboro, Gresham, Lake Oswego, Oregon City, Tualatin, Tigard – has the largest concentration of affiliated professionals and the widest range of price points. PPB officers, OHSU nurses, Portland Fire and Rescue, and Portland Public Schools teachers are the most common hero profiles I work with in this market.
Bend and Central Oregon
Bend’s median price has climbed significantly and the Homes for Heroes realtor reward at $875,000 median is among the highest in Oregon at ~$6,125. Healthcare workers at St. Charles and heroes relocating to Central Oregon are active in this market. The savings offset is meaningful at these price points.
Eugene and the Willamette Valley
University of Oregon and Lane Community College employees, PeaceHealth nurses, and Eugene Police and Fire make up most of the hero activity in this market. Eugene is one of Oregon’s more affordable larger cities, and the Homes for Heroes savings stretch further at lower price points relative to income.
Salem
State government employees, Oregon State Hospital staff, Salem Police and Fire, and Salem-Keizer School District teachers are all active in this market. Salem tends to be more affordable than Portland and Eugene, with a stable market that suits heroes on predictable public sector salaries.
Rural Oregon
The Homes for Heroes network is less dense in rural areas, but heroes in every corner of Oregon deserve the same access. If you’re looking outside the major metros, contact me. I’ll find the right affiliated professionals closest to you.
FAQ
Frequently Asked Questions
Do I have to be a first-time homebuyer?
No. Homes for Heroes works for any purchase or refinance, regardless of how many times you’ve owned a home before.
Can I use this to refinance?
Yes. Heroes receive lender savings on refinances. The realtor reward only applies to purchase and sale transactions.
Do I have to use a specific lender or real estate agent?
To get the full benefit, yes, you need both a Homes for Heroes affiliated realtor and a lender. I’m the lender. I can refer you to vetted affiliated agents in your target area throughout Oregon.
What if I already have a realtor I like who isn’t affiliated?
You’d lose the realtor reward (0.7% of purchase price) but still receive lender savings by working with me. Worth having the conversation before you commit to an agent; the realtor reward is typically the larger portion of the savings.
When does the hero rewards check arrive?
Typically 5-7 days after closing on your purchase or sale.
Are there income limits or restrictions on the home?
No income limits from Homes for Heroes. No restrictions on property type or location. The only requirement is that you qualify in one of the five hero categories and work with affiliated professionals.
Can I combine this with a VA loan?
Yes. VA loan benefits are separate from Homes for Heroes. Zero down payment on the VA side, realtor reward and lender savings on the Homes for Heroes side. Veterans should strongly consider using both.
Does this work in rural Oregon?
Yes. If you’re outside the major metros, contact me. I’ll connect you with the right affiliated professionals in your area.
I’m retired. Do I still qualify?
Yes. Retired heroes in all five categories qualify for the program.
Find Out What You Save
Tell me where you’re looking and your target price range. I’ll give you a personalized estimate of what Homes for Heroes saves you: realtor reward, lender savings, and anything else you might qualify for in your specific area.
Your service earned this. Let’s use it.
Shannon McAlister | (503) 516-8881 | home-owners-pdx.com
Luminate Bank | Portland, Oregon | Licensed in Oregon and Nationwide | NMLS #885982
Shannon McAlister is a Certified Mortgage Advisor and mortgage lender based in Portland, Oregon. With 20+ years in the business, she specializes in real estate investors, reverse mortgages, and divorce mortgage planning as an RCS-D certified professional. Oregon Homes for Heroes affiliate for 12+ years. The kind of lender you refer your people to. home-owners-pdx.com | NMLS #885982
This article is for educational purposes. Loan terms, rates, and program details are subject to change. Contact directly for current program availability and qualification requirements.
Did you know that over 1.5 million games were bowled at the Kellogg Bowl during its six-decade run? This staggering number reflects the cultural footprint of a cherished local institution that closed its doors in 2020, leaving a community heartbroken.
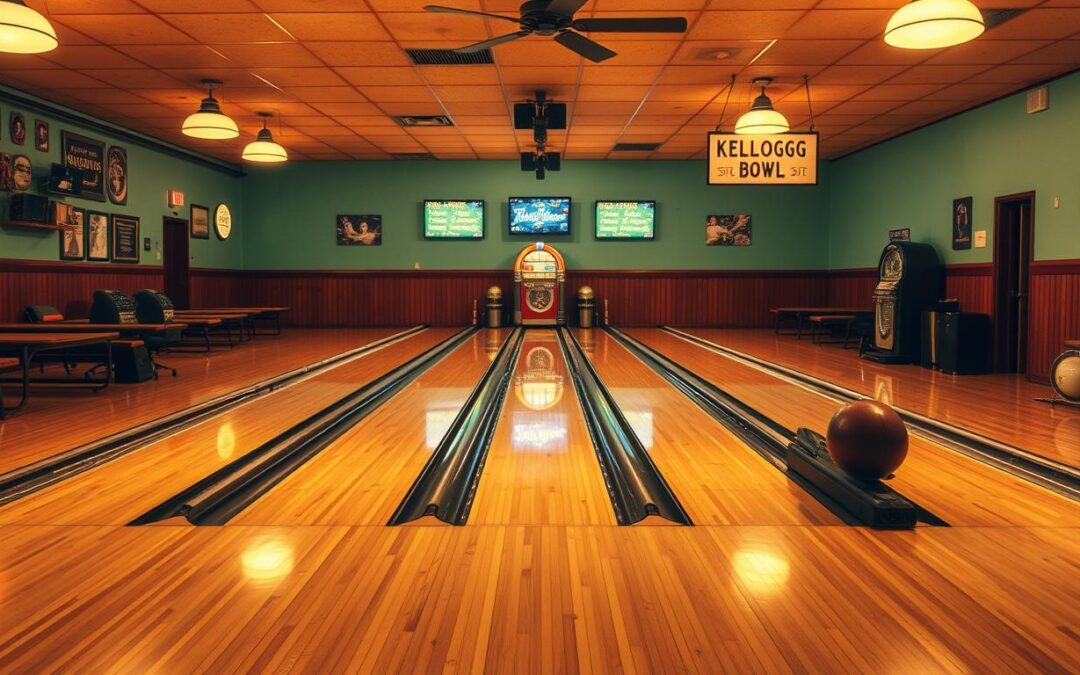
For 58 years, this family-operated Kellogg Bowl landmark served as Milwaukie’s living time capsule. Its retro neon glow and vintage lanes hosted first dates, birthday parties, and championship tournaments. Regulars still recall the distinctive clatter of wooden pins echoing through the unchanged mid-century interior.
The closure didn’t just end a business – it erased a piece of Pacific Northwest history. Owners Bill Oetken and Champ Husted fought to preserve their establishment through 12 months of pandemic restrictions. Despite community support, the financial strain proved insurmountable for the multigenerational gathering spot.
This story isn’t just about lost strikes and spares. It’s about how local businesses become the glue holding neighborhoods together. As we explore this venue’s journey, you’ll discover why its neon sign symbolized resilience – and what its absence means for America’s disappearing recreational landmarks.
Operated continuously for 58 years before 2020 closure
Featured iconic retro design elements preserved since 1962
Hosted multiple generations of local families and leagues
Closed due to pandemic-related financial challenges
Represented a significant cultural loss for Oregon
Highlights struggles of family entertainment venues
Historic Roots and Community Impact
In 1962, a new gathering spot opened its doors just south of Portland, quickly becoming the heartbeat of neighborhood fun. For nearly six decades, this family-run establishment operated with a simple philosophy: keep it welcoming, keep it real.
Tracing the Family-Owned Tradition
Bill Oetken and Champ Husted poured their hearts into maintaining the venue’s original charm. Their secret? Treating every visitor like extended family. General manager Roxanne Oetken became the smiling face regulars looked for, ensuring kids learned proper lane etiquette while veterans kept their favorite scoring systems.
Milwaukie’s Role in Local Entertainment History
While bigger cities embraced flashy arcades, this Clackamas County gem stayed true to its roots. The retro neon sign glowing since JFK’s presidency became a beacon for those craving genuine connection. It wasn’t just about rolling balls – it hosted charity events, league rivalries, and three generations of birthday celebrations.
Locals often joked the 1960s-era ball returns had more personality than modern automated systems. This commitment to authenticity made the venue a living museum of mid-century recreation, earning recognition as one of Oregon’s longest-running family businesses.
Challenges During the Pandemic: Kellogg Bowl Bowling Alley
The COVID-19 pandemic delivered a crushing blow to local entertainment venues across Oregon. For this family-run establishment, what began as a temporary shutdown in March 2020 became a devastating fight for survival. State health mandates forced doors closed just as league seasons were gaining momentum, leaving regulars and staff reeling.
State Health Restrictions and Temporary Closures
Initial optimism about a brief closure faded as coronavirus cases surged. The business joined dozens of recreation centers statewide in what owners called “financial limbo.” Revised guidelines in October 2020 brought cautious hope, allowing limited operations at 50% capacity.
Staff reconfigured lanes for social distancing and installed sanitizing stations. However, the relief proved short-lived. A state-ordered freeze in November abruptly halted operations again, creating impossible choices about payroll and maintenance costs.
The Impact of Financial Hardship on Operations
Ten months of intermittent closures drained resources. Fixed expenses like insurance and equipment repairs continued while revenue streams dried up. “We watched our life’s work gather dust,” one owner recalled, noting most relief programs favored larger corporations.
The final closure decision in December 2020 echoed through the community. With 58 years of history at stake, owners emphasized they’d “exhausted every option.” Their statement highlighted the harsh reality: no small business could withstand 12 months of uncertainty without sustainable support systems.
Enduring Stories of Milwaukie Bowling Culture
Behind every closed business lies human stories that outlast polished lanes and neon signs. The true legacy of this cherished gathering place lives through those who kept its spirit alive.
Experiences from Owners and Managers
General manager Roxanne Oetken’s voice cracked as she described the final months: “We’ve been sitting there since May ready to go. Every day got harder.” Her words mirrored the plight of family-run entertainment venues nationwide. Bill Oetken and Champ Husted built relationships where staff knew regulars’ shoe sizes and favorite lanes.
A heartfelt Facebook post to patrons revealed their gratitude: “Your support has been our heart.” This bond transformed casual visitors into extended family over six decades.
Community Engagement and Loyal Patrons
When state restrictions lingered, bowlers organized rallies at six Portland area bowling centers. Regulars shared how league nights provided crucial social connections – particularly for retirees. 72% of senior patrons reported the venue was their primary community hub.
Comparisons to Other Portland Area Alleys
The 2020 closures claimed multiple landmarks, including Wilsonville Lanes. Unlike corporate-owned bowling centers, these family-operated spots offered personalized experiences. Their vintage charm and staff continuity created atmospheres modern venues struggle to replicate.
As one longtime bowler noted: “Other alleys have laser lights. We had Roxanne remembering everyone’s birthday.” This human touch made the difference between generic entertainment and cherished tradition.
Conclusion
The final frame has been bowled at a cherished Oregon landmark. Kellogg Bowl’s permanent closure leaves a gap in the Portland area that modern entertainment hubs can’t fill. For 58 years, this family-owned bowling alley connected generations through shared strikes, gutter balls, and birthday cake smears.
Owners Bill Oetken and Champ Husted exemplified resilience during the coronavirus crisis. Their staff worked tirelessly through 12 months of changing restrictions, embodying the spirit that made small businesses community anchors. Their story mirrors Oregon’s broader struggle—41 of 49 bowling centers statewide closed during the pandemic.
Regular bowlers still recall the clatter of vintage pinsetters and Roxanne Oetken’s welcoming smile. These memories outlast the business itself, reminding us how local gems shape neighborhoods.
The owners‘ final message offered hope for surviving alleys: “May others keep rolling strikes for future generations.” As corporate chains dominate leisure spaces, we must cherish remaining centers preserving authentic connections.
Though lanes lie quiet here, the legacy lives through every child learning to bowl and every league rivalry rekindled elsewhere. Some traditions deserve extra frames.
The new year has arrived, making it the ideal moment to map out your goals for 2025. If finding a new home is on your wish list, you’re in luck! Wondering where to begin? Relax, we’re here to guide you every step of the way. With a clear, actionable game plan, we’ll help you turn your dream into a reality with ease.
Find Your Why: How Your Motivation Shapes the Right Mortgage Choice
Before diving into the logistics, take a moment to reflect on why you want to make a move. While the financial details are important, your motivation is the driving force behind every decision. Are you seeking more room to accommodate your growing family? Maybe you’re ready to downsize and embrace a simpler lifestyle. Or perhaps it’s finally time to step into the world of first-time homeownership. Whatever your reason, keep it at the forefront—it’s what will fuel your determination through every step of the process.
Sharing your “why” with your mortgage expert helps them tailor their guidance to meet your unique needs. They’ll ensure your goals are aligned with the best possible loan options. No matter the market conditions, a skilled agent will guide you through challenges, keep you focused, and turn your vision into reality.
Get Clear on What You Need: Build Your New Home Wishlist
Next, it’s time to dream a little, and get practical. What does your new home absolutely need? Think about things like:
How many bedrooms you’ll need
If a home office is a must-have
Whether you want a big fenced-in backyard for pets or kids
Having a clear list of your must-haves (and nice-to-haves) will make your search a whole lot smoother. If your budget is tight, flexibility might be key. Maybe you can expand your search area or compromise on one feature if another must-have is met. Share your wishlist with your agent—they’ll help you prioritize and focus on homes that check the right boxes.
Know Your Numbers: Financial Prep for a Stress-Free Mortgage Journey
Before you dive into open houses or start scrolling through listings, take a close look at your finances. Ask yourself:
How much have you saved for a down payment?
What monthly payment feels comfortable for you?
It’s also important to partner with the right pros like a trusted lender and real estate agent. Together, they can help you:
Plan for your down payment (and explore any assistance programs available).
Understand how much equity you have in your current home if you’re selling.
Get pre-approved for a mortgage, so you know exactly how much you can borrow.
Being clear on your numbers from the start makes everything easier and less stressful.
Build Your Expert Team: Why a Mortgage Lender and Agent Are Key to Your Success
Buying or selling a home is one of life’s biggest decisions, and having the right support can make all the difference. Choosing an expert team, including a skilled mortgage lender and real estate agent, is essential to navigating the process smoothly and avoiding unnecessary stress. A knowledgeable lender will help you understand your financing options, secure pre-approval, and ensure your budget aligns with your goals. Meanwhile, a great real estate agent understands the market, answers your questions, and guides you through every step. As Bankrate puts it:
“. . . now more than ever, it’s smart to lean on the guidance of an experienced local real estate agent. If you want to enter the housing market in 2025, whether as a buyer or a seller, let a pro lead the way for you.”
With the right professionals in your corner, you’ll gain the confidence to make informed decisions and stay on track toward your goals. We’re here to ensure you have the tools, resources, and expert guidance you need every step of the way.
Bottom Line: Make it Happen in 2025!
If buying or selling a home is on your list of goals for 2025, let’s make it happen! Focus on your why, get clear on your needs, and team up with the right pros (hint: that’s us!). This could be the year you check “new home” off your to-do list, and we’re here to cheer you on and light the way.
Ready to start? Let’s connect and make 2025 your brightest year yet! 💫
Last Friday’s jobs report was tough on rates. Mortgage bonds ended the day -61bps and we’re down another 12bps this morning.
Important notes for understanding and using this information:
Any site/chart that advertises rates (like the above) is showing a national average for one very specific loan scenario, as reported by survey respondents. These aren’t the rates that borrowers are locking in. Use this only as a tool to get a gauge of what ballpark to expect
30 Yr Fixed Conventional: a “top tier” scenario is used as a baseline (owner occupied, single family, 25% down, 780+ credit)
Most important point: the best use of this index is to track the CHANGE from week to week. There are so many things that can cause discrepancies between borrowers, lenders, and quotes.
Commentary
Hotter than expected jobs data Friday sent yields higher with the 10-year yield reaching recent highs not seen since November of 2023. Globally yields are moving higher with many traders anticipating a slowing of rate cuts this year with the Fed remaining cautious amid signs of economic strength mixed with potential policy changes as Trump takes office.
Officially known as The Employment Situation, the jobs report is the most comprehensive monthly update on the state of the labor market in the U.S. It’s also the economic report that has the greatest potential to cause volatility for interest rates. In general, higher levels of employment coincide with higher interest rates, but the traders that determine rates are less focused on the unemployment rate and more focused on the jobs report’s headline component: nonfarm payrolls (NFP). NFP is quite simply a count of the number of jobs added to or removed from the economy on any given month.
Market participants are anxiously awaiting PPI and CPI releases Tomorrow and Wednesday respectively.Recent PPI data suggests that inflation is moving higher again. Mortgage rates will likely print higher this morning and remain under upward pressure as yields continue to trend higher in the short run.
Lock/Float Considerations
Locking bias: don’t risk it.
Strong jobs report reinvigorates the upward trend in rates. The upcoming CPI data can take the pain to the next level or help create some support. In general,this is a lock-biased environment until such time as the data takes a cohesive and decisive turn in a rate-friendly direction. That’s not to say there won’t be pockets of short-term opportunities, but capitalizing on them would involve luck rather than strategy.
Econ Calendar – Potential Market Movers
Core: excludes food and energy
Tuesday, Jan 14
Core PPI & PPI (Producer Price Index), m/m
Change in the price of finished goods and services sold by producers. It’s a leading indicator of consumer inflation – when producers charge more for goods and services the higher costs are usually passed on to the consumer
Wednesday, Jan 15
Core CPI & CPI (Consumer Price Index), m/m
Change in the price of goods and services purchased by consumers. Consumer prices account for a majority of overall inflation.
CPI, y/y
Thursday, Jan 16
Retail Sales, m/m
The primary gauge of consumer spending, which accounts for the majority of overall economic activity